
The Monetary Policy Council (RPP) made the long-awaited decision at its meeting on 3–4 March 2026 and resumed its cycle of interest rate cuts. After a two-month pause (no changes in January and February 2026), the National Bank of Poland’s reference rate was cut by 25 basis points — from 4.00% to 3.75%. The other rates also fell by the same amount: the lombard rate to 4.25% and the deposit rate to 3.25%.
The decision was widely expected by analysts at the largest banks (including ING, Credit Agricole, mBank, PZU and Santander). Most forecasts made at the beginning of March assumed a 25 bp cut, despite growing uncertainty linked to the escalation of the conflict in the Middle East and higher oil prices.
Why now?
The main arguments for a cut are:
- a sustained and broad-based decline in CPI inflation in recent months,
- the March NBP inflation projection, which confirmed inflation returning to around the 2.5% target (±1 percentage point),
- a marked slowdown in wage growth after the peak at the end of 2025,
- signs of weakening economic activity in Q1 2026 (weaker data from industry and construction).
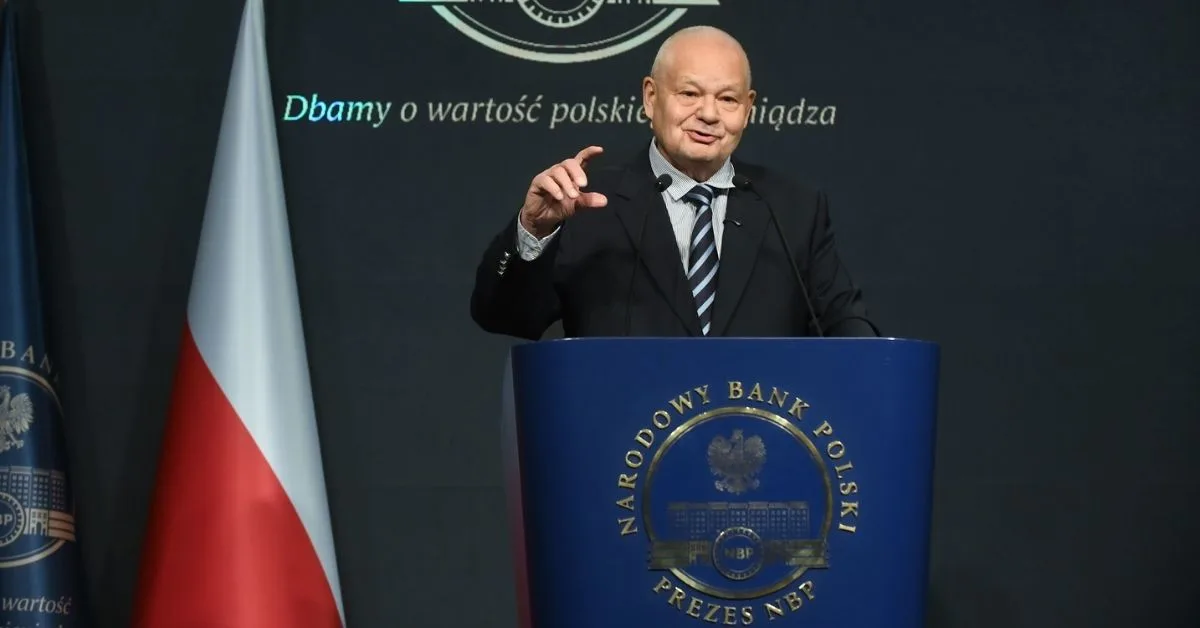
NBP Governor Adam Glapiński had repeatedly suggested in recent weeks that March would be a good moment to return to monetary easing — and so it happened.
How much will loan repayments in PLN fall?
The greatest relief will be felt by those repaying mortgages based on WIBOR 3M or WIRON 3M rates (currently the most popular).
Assuming typical examples (bank margin of 2.2–2.6%):
- Loan of PLN 400,000, remaining term 25 years → instalment before the cut ≈ PLN 2,650–2,750 → instalment after the cut ≈ PLN 2,560–2,660 Savings ≈ PLN 90–100 per month
- Loan of PLN 600,000, remaining term 22 years → instalment before the cut ≈ PLN 3,900–4,050 → instalment after the cut ≈ PLN 3,770–3,920 Savings ≈ PLN 130–150 per month
- Loan of PLN 350,000, remaining term 18 years → instalment before the cut ≈ PLN 2,480–2,580 → instalment after the cut ≈ PLN 2,400–2,500 Savings ≈ PLN 80–90 per month
The first lower instalment should appear in most cases in April or May 2026 (depending on when the interest rate in the loan agreement and the bank are updated).
What next for rates in 2026?
The market and economists currently expect 2–3 further cuts in 2026 (50–75 bp in total), which could bring the reference rate down to around 3.25–3.50% by the end of the year. However, the pace of further cuts will depend heavily on:
- developments in the geopolitical situation and commodity prices,
- the pace of disinflation in Q2–Q3,
- data from the labour market and consumption.
For now, borrowers can breathe a sigh of relief — the first real reduction in instalments in over two months is a fact. Future RPP decisions will show whether this positive trend for holders of PLN loans will hold.