

They promised to abolish the Belka tax. It was supposed to be simple, fair and motivating. Instead, we will get a new financial instrument at the end of 2026.
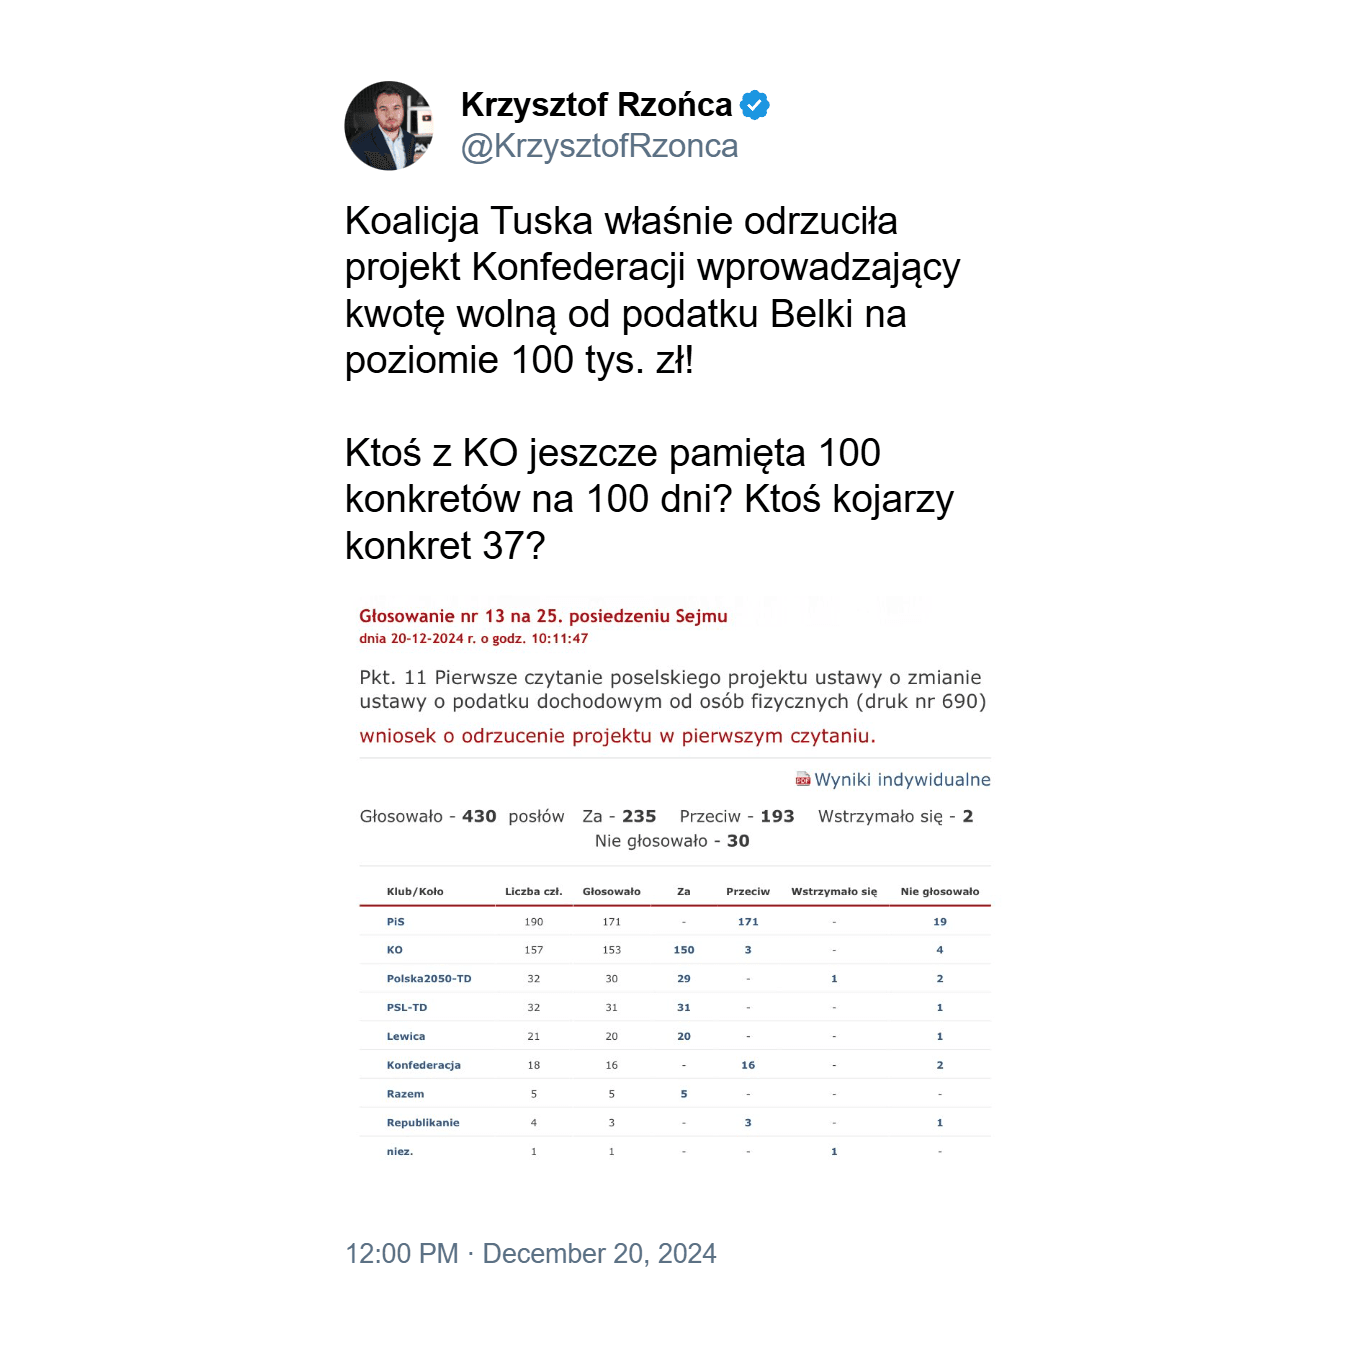
In the 2023 election campaign, the Civic Coalition (KO) promised “100 concrete steps in 100 days”. Item number 37 clearly stated: abolish the Belka tax on savings and investments of up to PLN 100,000 held for longer than a year. Today we know this promise will not be kept.
Instead, the Ministry of Finance and Economy (MF) (yes, the ministry changed its name in July) has announced a new instrument: the Personal Investment Account (OKI). The idea? Instead of abolishing the tax for everyone, a new product is being created. People will also have to wait until the second half of 2026 for it.
A new financial instrument instead of real reform
According to an announcement by Minister Andrzej Domański, OKI is to allow Poles to invest up to PLN 100,000 without the Belka tax, with amounts above that taxed at a preferential rate of roughly 0.8-0.9% per year. The idea is inspired by the British ISA (Individual Savings Account), but in Poland the problem is not a lack of investment products. It is the mess, high taxation and complicated rules.
Some data on investing in Poland:
- Only 6% of Poles actively invest on the stock exchange (GPW, 2024).
- Among people aged 18–29, over 70% keep their money exclusively in savings accounts or cash (NBP, “Financial Diagnosis 2024”).
- Half of Poles cannot say how IKE differs from IKZE (BGK, 2023).
Even so, instead of simplifying the tax system, we are getting yet another instrument that only a few will understand. Yet it would be much easier to simply:
- introduce a tax-free allowance on capital income,
- design a progressive tax scale that does not treat a small investor the same as someone earning millions on the stock market.
IKE, IKZE, PPE, or how to discourage people from saving
It is not as if Poles have nowhere to invest. We have IKE and IKZE accounts, and some people are also offered Employee Pension Programmes (PPE). In theory, these are great products:
IKE: no Belka tax after reaching retirement age and meeting the conditions. Contribution limit for 2025: PLN 23,472.
IKZE: in addition, contributions can be deducted from income (limit: PLN 9,388.80 for people not running a business).
PPE: for the lucky few working in larger companies that agreed to offer this benefit.
Unfortunately, most Poles either do not know about these products, do not understand how they work, or simply do not believe the state will not change the investment rules again in a few years.
On top of that, all these products share one common feature: they are rigidly tied to retirement age, which for young people means their money is locked up for decades.
Investing is not a hobby but a necessity
You do not need to be an economist to know that future pensions from ZUS (the Social Insurance Institution) will be dramatically low. A twenty-year-old today who does not invest consciously most likely has no security for the future. Demographics in Poland are merciless, and living costs are rising. How is a young person supposed to be motivated to save when the state takes 19% Belka tax from every gain, even the smallest?
All the data and analyses point to one thing: young Poles want to invest, but often do not know how, which creates a need for simple and motivating ways to invest capital. The promise of “100 concrete steps” was a good move in this direction. Instead of delivering on it, we have another instrument that forces people to change their habits and has an uncertain future.

Komentarze