
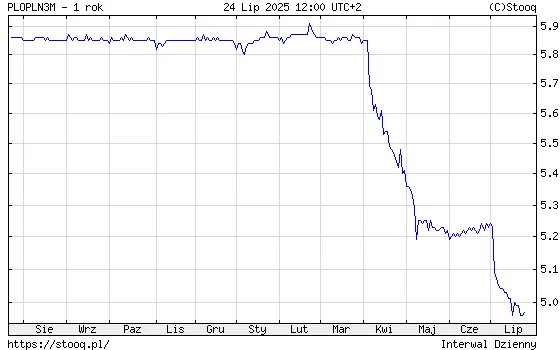
WIBOR 3M has dropped below the psychological 5% level for the first time in two years. Is the trend lasting, and what does it mean for your loan payment?
What happened to WIBOR?
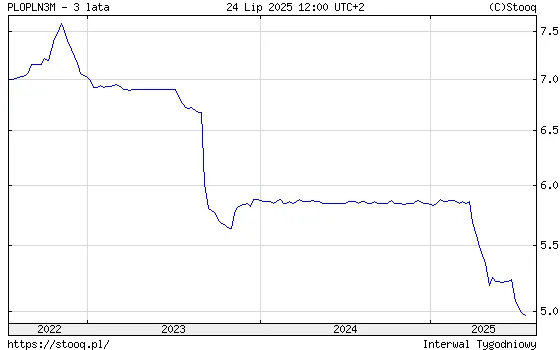
- On July 24, the WIBOR 3M rate stood at 4.97%.
- Since the September 2023 peak, the decline has exceeded 150 bps – the result of two summer rate cuts by the Monetary Policy Council (RPP) (totaling -75 bps).
- The next meeting on August 7 is non-decision-making, so any further rate cut would come only on September 3-4.
Will 5% hold?
Economists see room for further cuts, but not until autumn:
- The National Bank of Poland (NBP) July projection assumes an average WIBOR 3M of 5.37% in the second half of the year.
- PKO BP expects a total of -75 bps in cuts in 2025; the reference rate target is 3.5%.
In practice, the 5% level may be breached once more, especially before the September decision. The pace of disinflation and the zloty exchange rate will be key.
Loan payments – how much could you save?
Assumptions
- Loan: PLN 500,000
- Term: 30 years and 20 years variants
- Bank margin: 2.0% (typical at LTV ≤ 80%)
- Interest rate = margin + WIBOR 3M
| Scenario | Interest rate | 30-year payment | 20-year payment |
|---|---|---|---|
| WIBOR 3M 5.5% (start of year) | 7.5% | PLN 3,496 | PLN 4,033 |
| WIBOR 3M 5.0% (currently) | 7.0% | PLN 3,326 | PLN 3,830 |
| WIBOR 3M 4.5% (after another -50 bps cut) | 6.5% | PLN 3,162 | PLN 3,636 |
Payments calculated using the annuity method – each 50 bps rate cut equals approx. PLN 160-200 in monthly relief on PLN 500k.
What about loan holiday schemes?
The government has not announced a new edition of the programme. For now, only falling WIBOR provides real relief.
What are borrowers waiting for?
Key dates
- August 7 – meeting without a decision.
- September 3-4 – full RPP decision, potentially -25 bps or -50 bps.
- November – new inflation projection; if the CPI (consumer price index) approaches the 3.5% target, the cycle of cuts will accelerate.
How to prepare your household budget?
- Keep a cushion – your payment may fall more slowly than service inflation rises.
- Consider a fixed rate for 5 years if the bank offers <6% – it protects against a rebound in rates.
- Check whether an early loan repayment (even PLN 5,000) gives more relief than a 6% deposit.
WIBOR 3M has already brought an average of PLN 170 lower monthly payment per PLN 500k compared with January. If the RPP cuts rates by another 50 bps, the payment could fall by a further PLN 160. The 5% barrier will therefore be tested, but a sustained drop below 4.5% is a scenario for year-end. Borrowers need to be patient – further relief will most likely arrive only after September.